0800 994 9026
enquiries@foam-away.com

Spray Foam Removal vs Spray Foam Re Claim: What’s the Difference?

Energy Efficient Solution

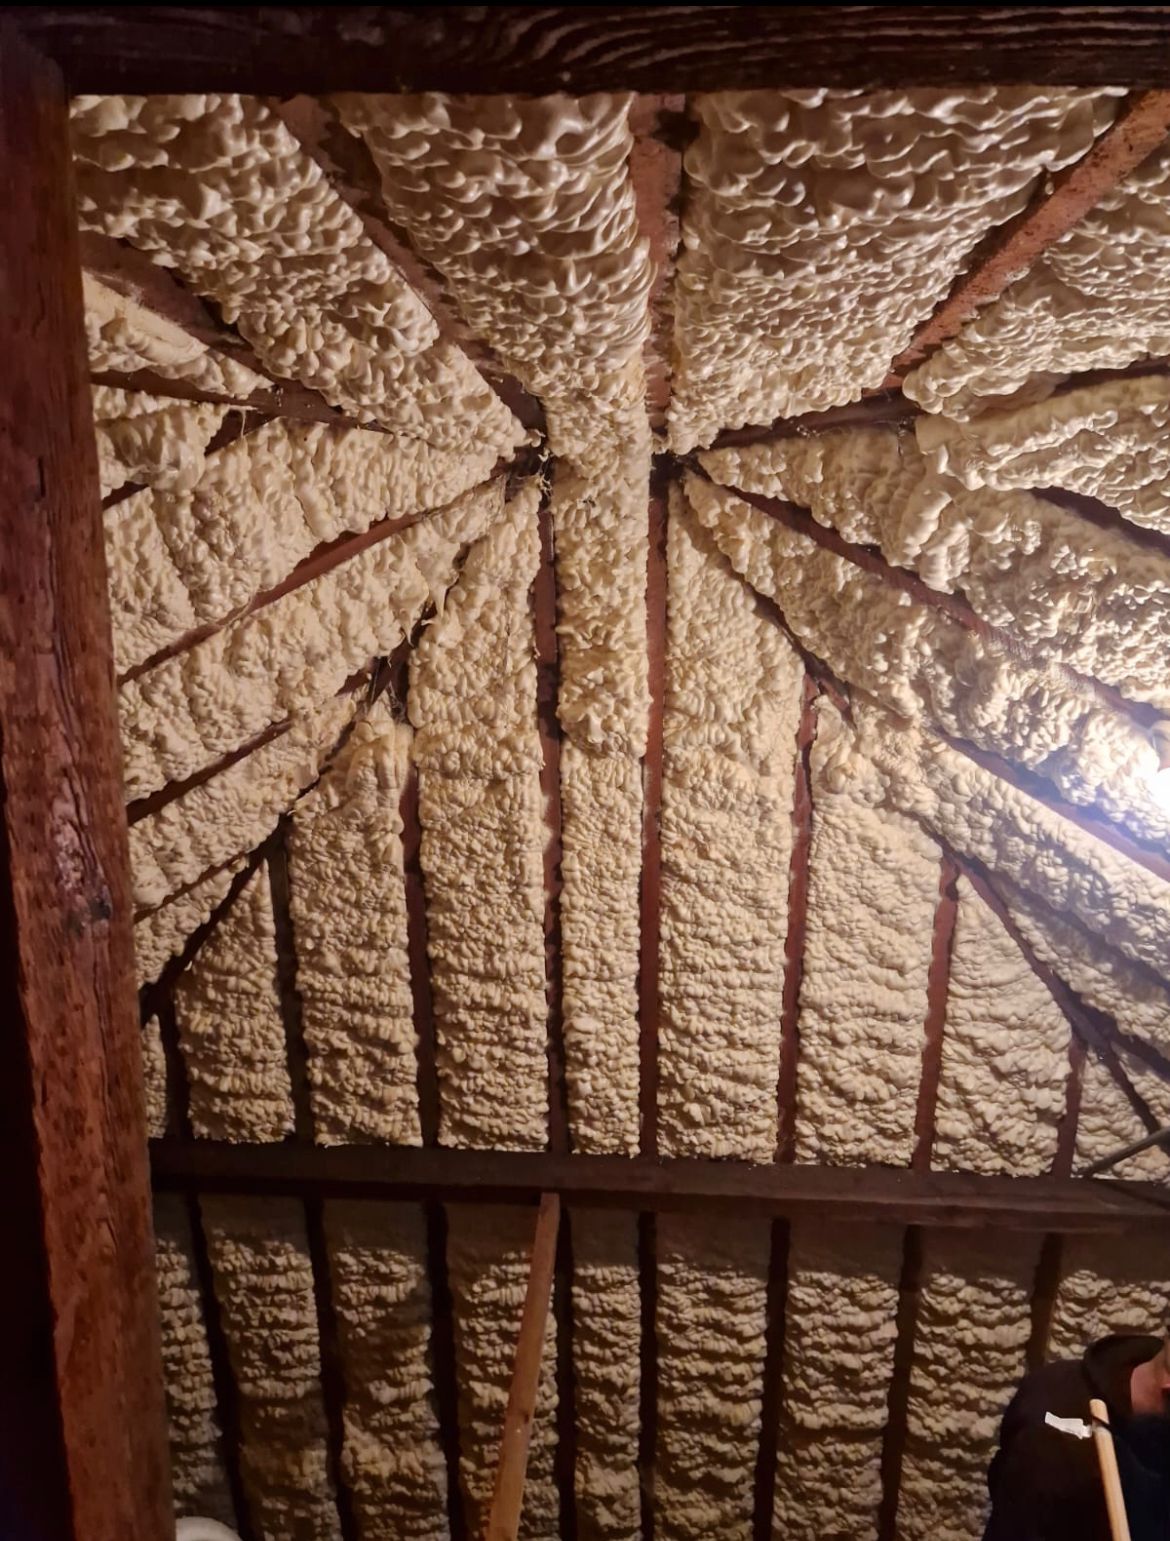
For many homeowners across the South Coast and the Midlands, spray foam insulation has become an unexpected obstacle. What was once marketed as a modern and energy efficient solution is now raising serious concerns during property surveys, remortgage applications, and house sales. Mortgage lenders are becoming increasingly cautious, surveyors are flagging spray foam loft insulation more frequently, and thousands of property owners are now searching for practical solutions.

Among the most common points of confusion is the difference between spray foam removal and spray foam re claim. While the two terms are often used interchangeably online, they refer to very different approaches. Understanding that distinction can help homeowners make informed decisions about their property, their roof structure, and their future mortgage options.

At Foam Away, homeowners across Bournemouth, Southampton, Portsmouth, Brighton, Birmingham, Leicester, Nottingham, and surrounding areas regularly ask the same question. Should the spray foam be completely removed, or can it be professionally re claimed and managed another way?

The answer depends on the condition of the roof, the type of spray foam installed, and the concerns raised during inspection.
What Is Spray Foam Insulation?

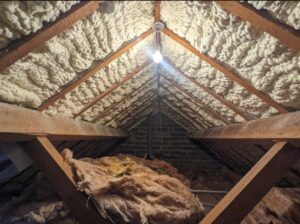
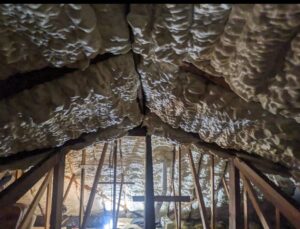
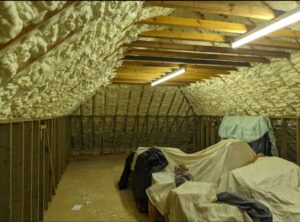
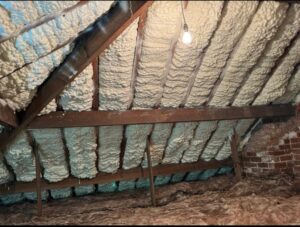
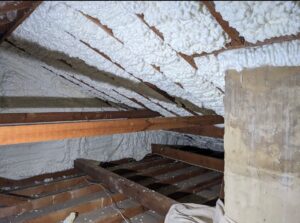
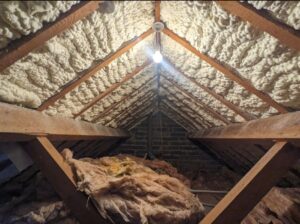
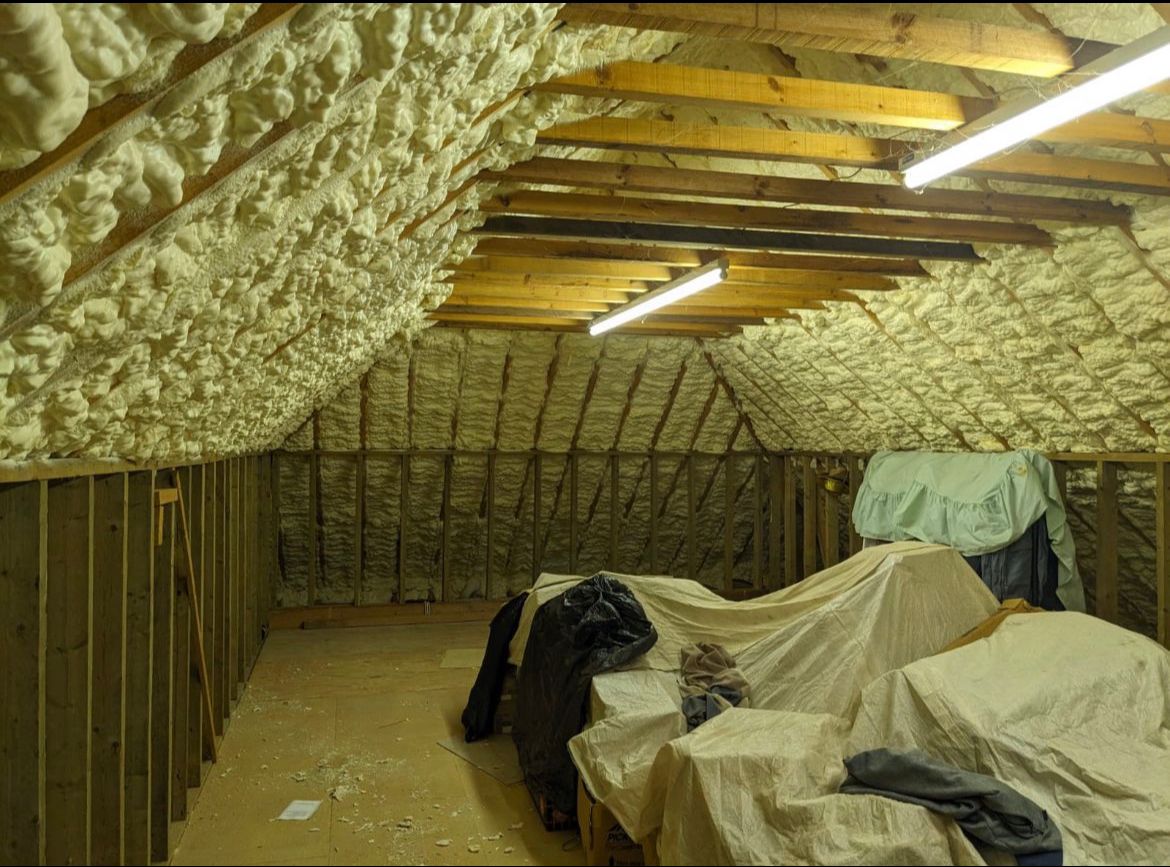
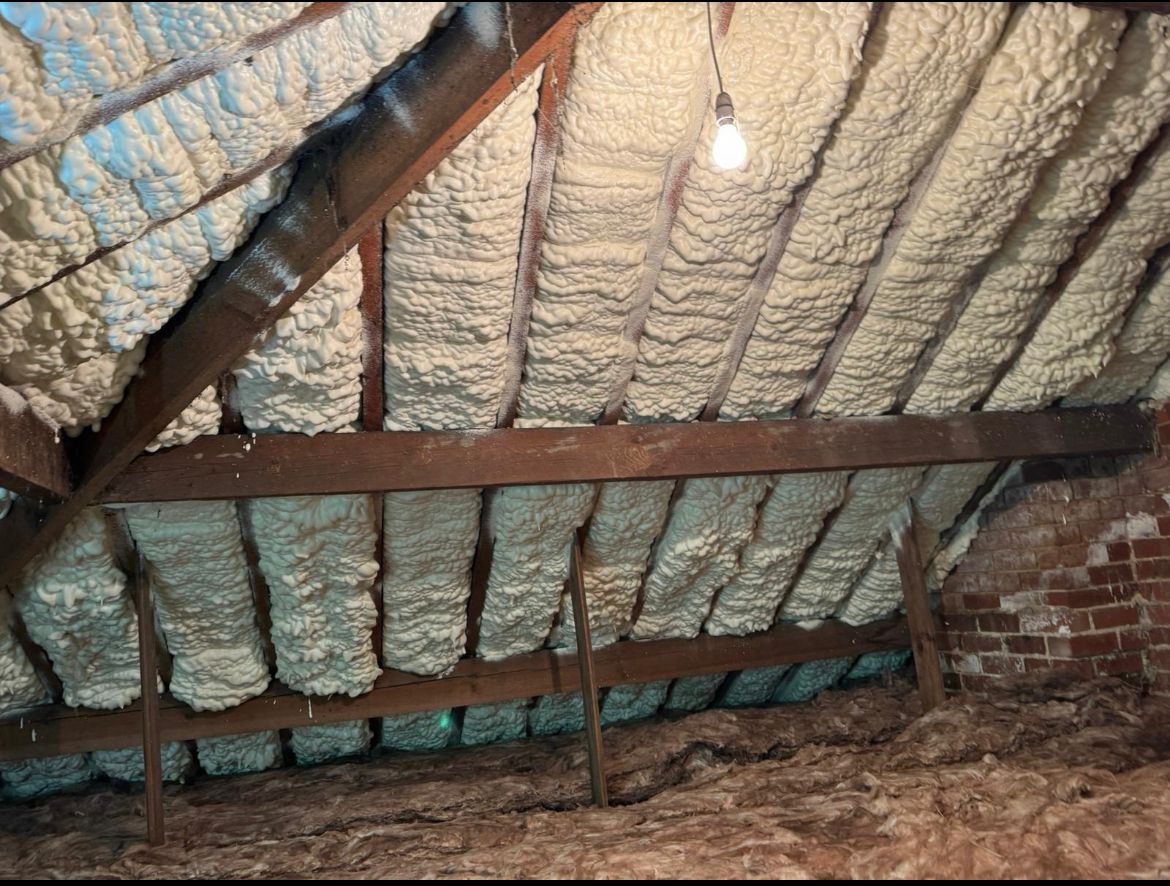
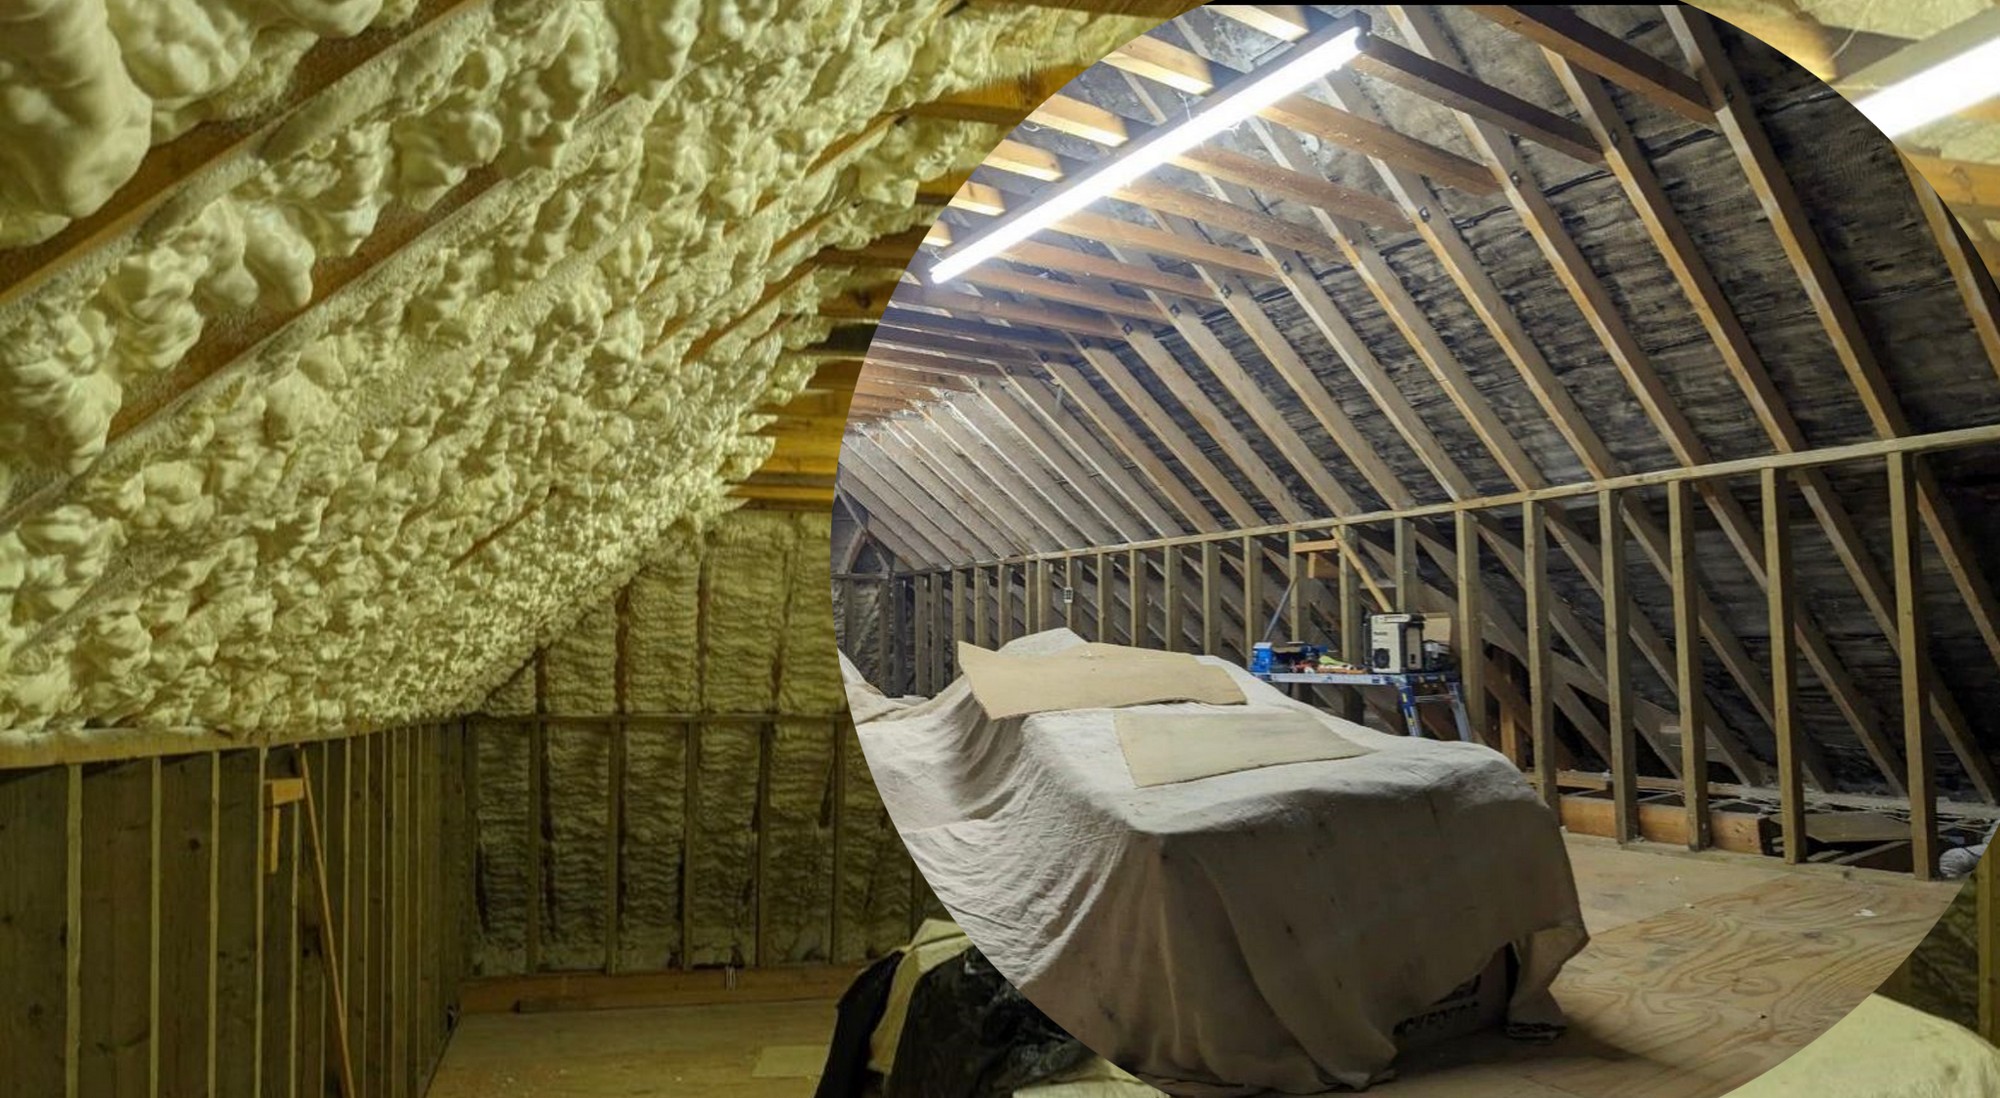
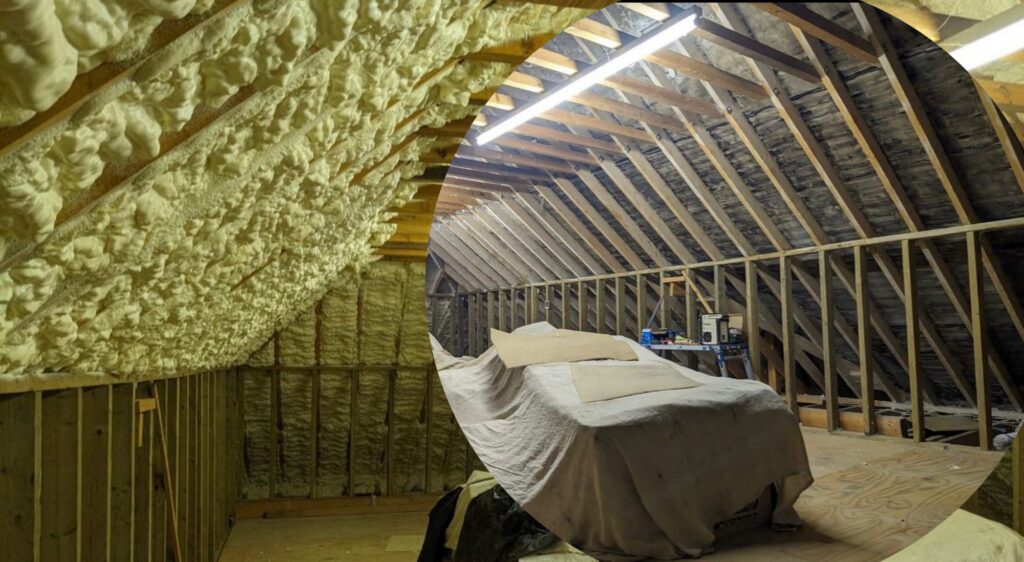
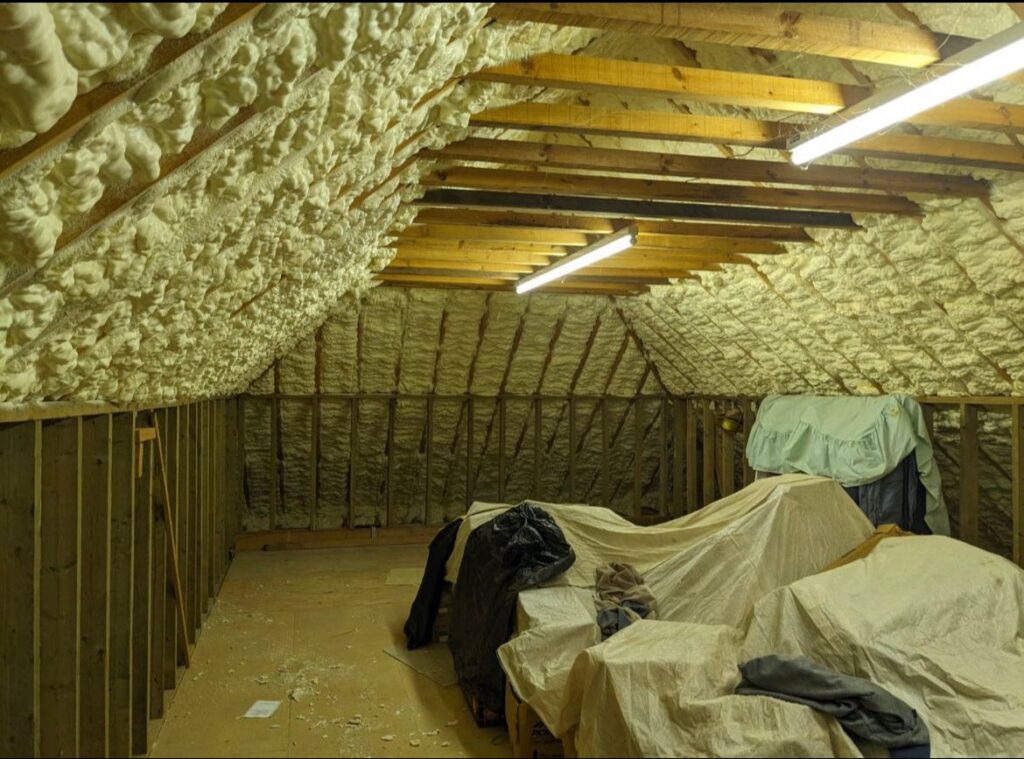
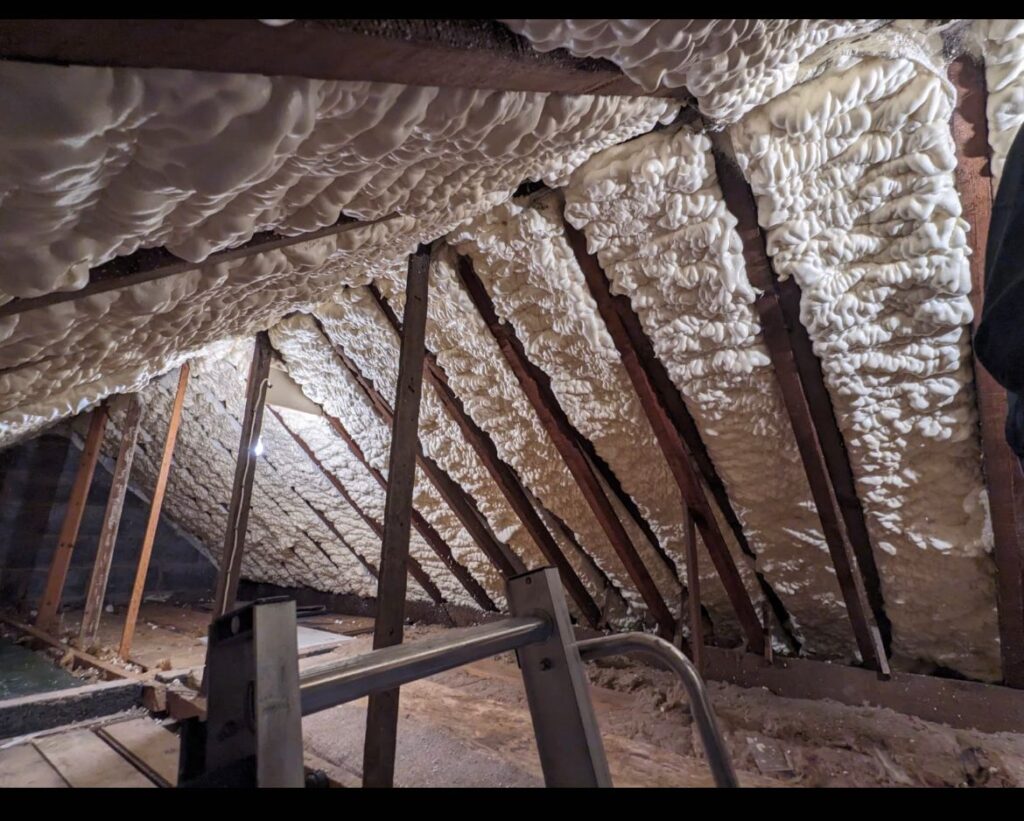
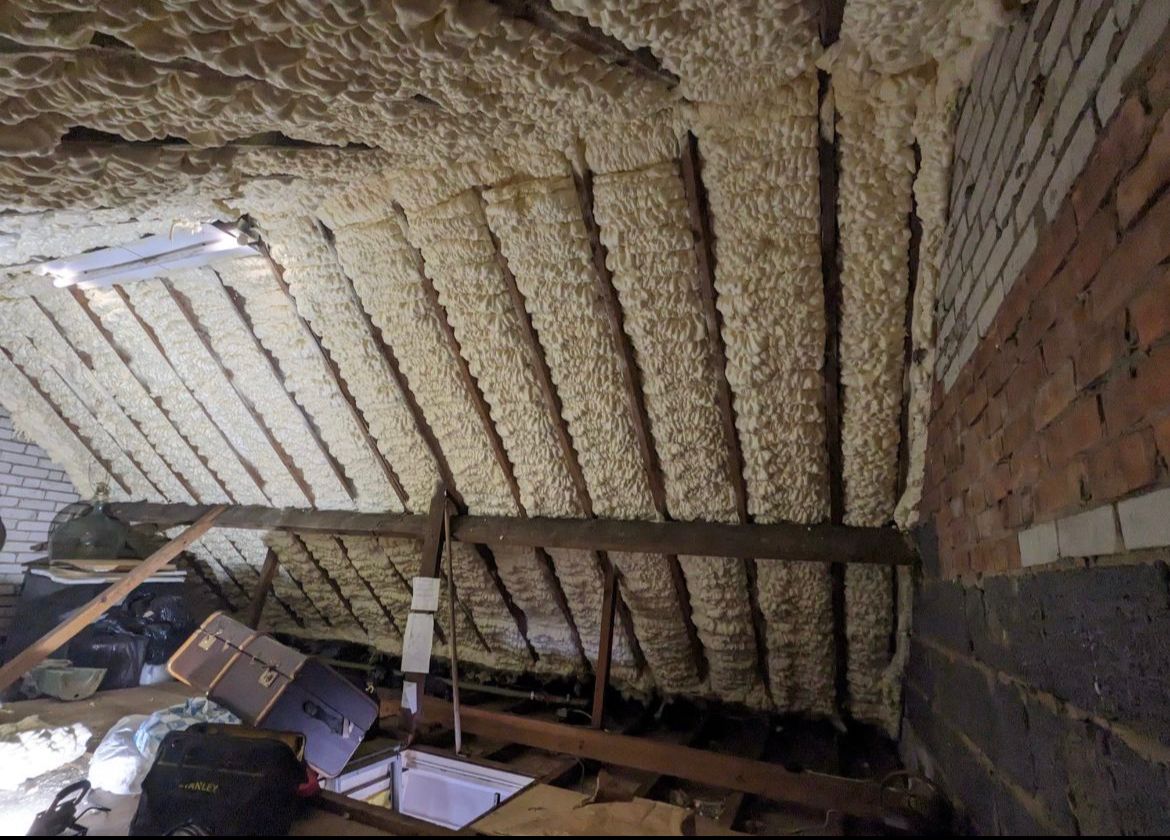
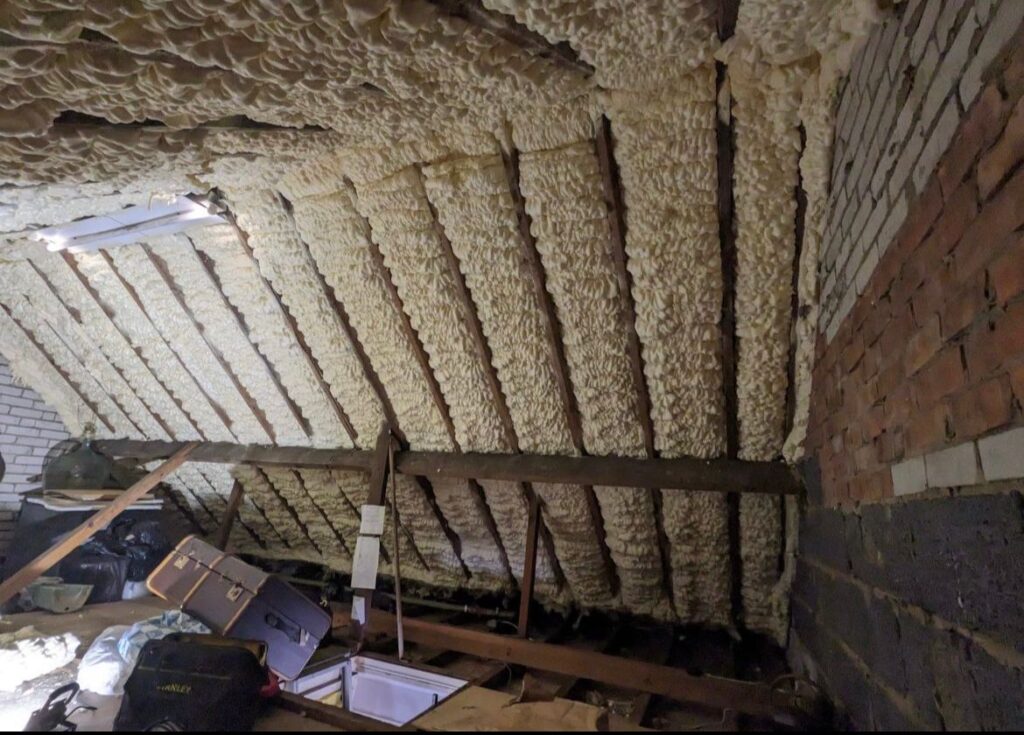
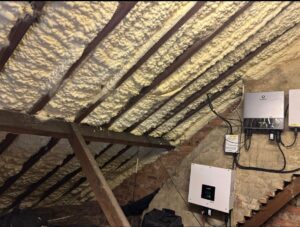
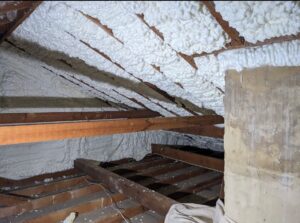
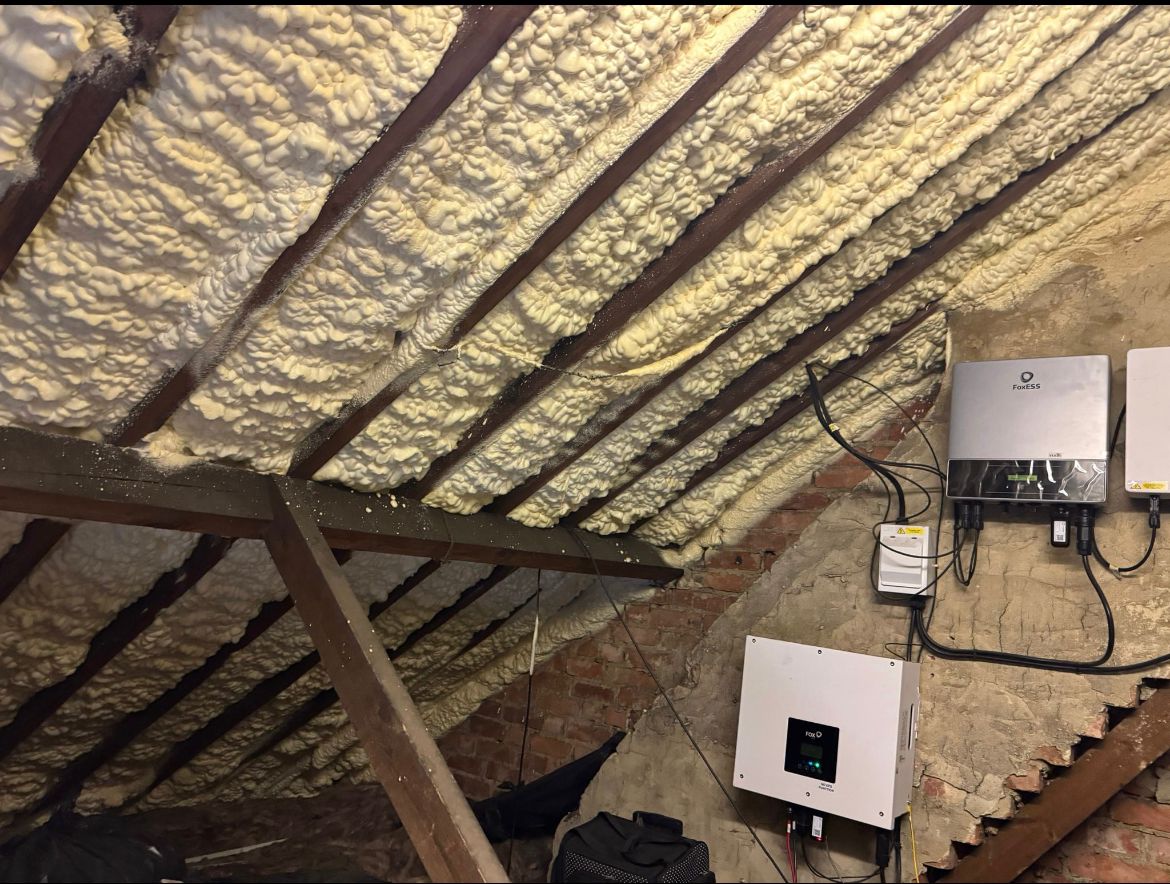
Spray foam insulation is applied directly to the underside of roof tiles or between rafters. Once sprayed, it expands rapidly and hardens into an insulating layer designed to improve energy efficiency and reduce heat loss.

There are two main forms of spray foam insulation used in UK properties.

Open Cell Spray Foam

Open cell foam is softer and more breathable. It allows a degree of moisture movement and is generally lighter in structure. Although some lenders view it more favourably than closed cell alternatives, it can still create issues during surveys and valuations.

Closed Cell Spray Foam

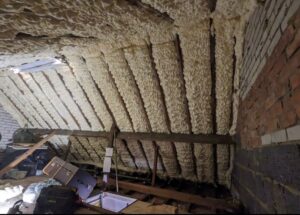
Closed cell foam is denser, harder, and far less breathable. While it offers strong insulation properties, it is also the type most commonly associated with mortgage concerns. Because it forms a rigid bond with roof timbers and tiles, surveyors often struggle to inspect the condition of the roof beneath it.

In many cases, this inability to inspect hidden roof structures is precisely why lenders become hesitant.
Why Are Mortgage Lenders Concerned About Spray Foam?

The growing issue surrounding spray foam insulation is not necessarily the insulation itself. The real concern lies in what may be hidden beneath it.

When spray foam is applied directly to roof felt and timber, it can restrict airflow and trap moisture. Over time, this may contribute to condensation, timber decay, or hidden structural deterioration. Because surveyors cannot always see what is happening underneath the foam, many mortgage lenders consider the risk too high.

As a result, homeowners are increasingly facing situations where:

  • Mortgage applications are declined
  • Remortgages are delayed
  • Buyers withdraw from sales
  • Surveyors recommend further investigation
  • Roof inspections become more complex and costly

This has led to a significant rise in demand for professional spray foam removal services across England.
What Is Spray Foam Removal?

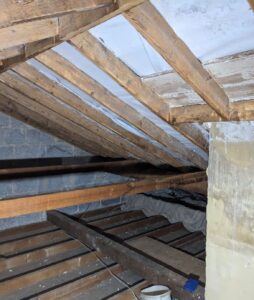
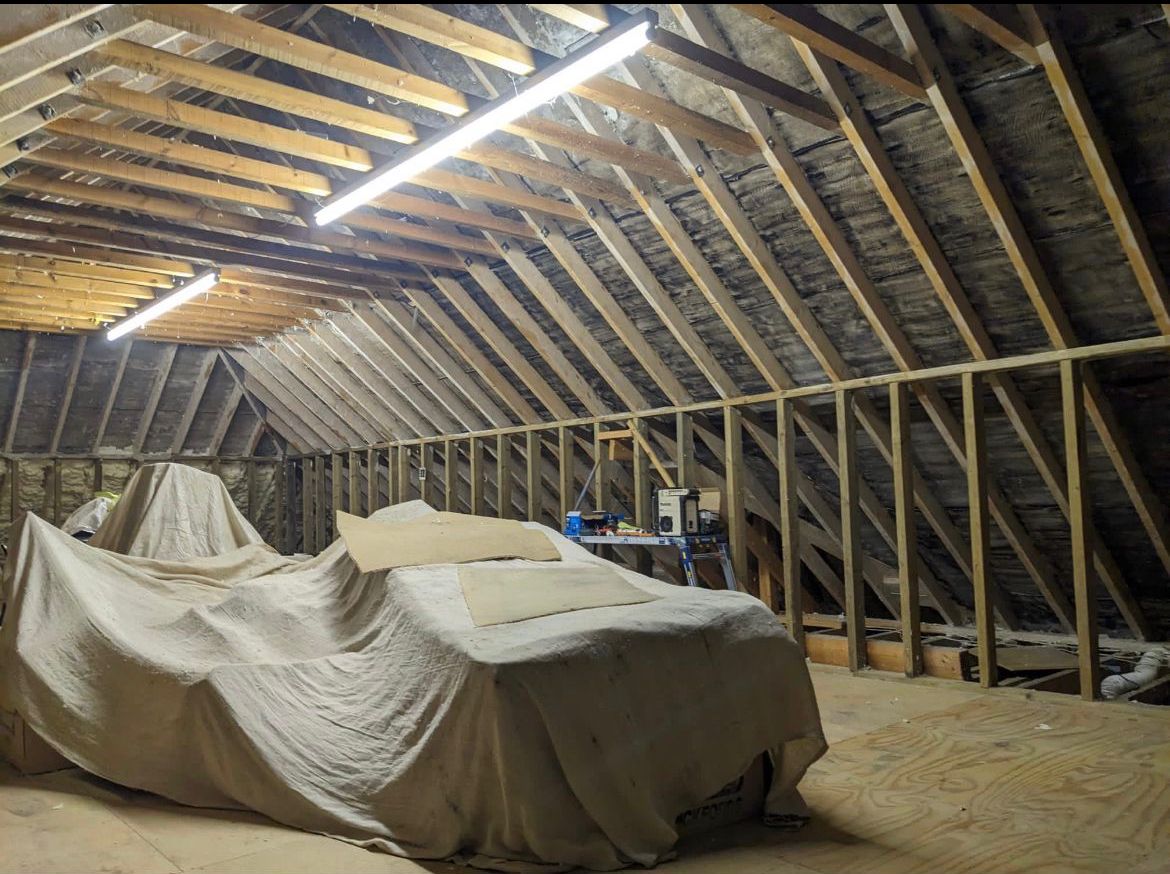
Spray foam removal involves the physical extraction of the insulation from the loft or roof structure. The objective is to restore visibility and access to the roof timbers, tiles, and felt beneath the foam.

Professional removal specialists use a combination of tools, techniques, and careful extraction methods to remove the foam while minimising damage to the roof structure.

In most cases, the process includes:

  • Assessing the condition of the loft and roof
  • Identifying the type of foam installed
  • Carefully removing the insulation from rafters and surfaces
  • Inspecting the roof structure beneath
  • Clearing waste materials from the property
  • Advising on ventilation or replacement insulation if required

For homeowners dealing with mortgage problems, full removal is often the most straightforward solution. Many lenders and surveyors prefer complete removal because it allows the roof structure to be properly inspected again.

What Is Spray Foam Re Claim?

Spray foam re claim is a more nuanced process. Rather than completely stripping the foam away, re claim focuses on managing or partially removing problematic sections while preserving areas that may still be functioning safely.

In some situations, only specific sections of spray foam are causing concern. A professional assessment may determine that targeted removal, ventilation improvements, or corrective work can address the issue without requiring full extraction.

Re claim solutions can include:

  • Removing foam from critical inspection areas
  • Improving loft ventilation
  • Addressing moisture concerns
  • Correcting poorly installed sections
  • Providing professional reports or assessments

The purpose of re claim is not simply to avoid removal costs. Instead, it aims to determine whether a less invasive solution can still satisfy structural concerns or survey requirements.

However, it is important to understand that re claim is not suitable in every case. Some lenders will still insist upon complete removal before approving a mortgage.
The Main Difference Between Removal and Re Claim

The distinction ultimately comes down to extent and purpose.

Spray foam removal seeks to eliminate the insulation entirely so that the roof can be fully inspected and restored to a more conventional condition.

Spray foam re claim seeks to manage the existing installation through corrective action, selective removal, or remediation work.

Removal is generally more comprehensive, while re claim is often more situational.

A homeowner facing an urgent mortgage rejection may require complete removal to satisfy lender requirements. Another property owner with minor survey concerns may benefit from a more tailored re claim approach.

Every property is different, which is why professional assessment is essential.

When Is Full Spray Foam Removal Recommended?

There are several situations where complete removal is usually considered the safest and most practical route.

Mortgage or Remortgage Problems

If a lender has specifically requested removal, partial measures are unlikely to resolve the issue. Full extraction often becomes necessary to proceed with the mortgage.

Signs of Roof Deterioration

If moisture, condensation, timber decay, or poor ventilation are discovered beneath the foam, removal allows the roof structure to be properly repaired.

Closed Cell Foam Installations

Because closed cell foam bonds tightly to roof materials, it is often viewed as the higher risk option. Many surveyors recommend removal as a precaution.

Preparing a Property for Sale

Removing problematic insulation before listing a property can help avoid delays later in the conveyancing process.
When Might Re Claim Be Appropriate?

There are also cases where a more measured solution may be suitable.

Minor Survey Concerns

If the spray foam is not causing visible damage and only limited inspection access is required, selective remediation may resolve the issue.

Open Cell Foam Installations

Some open cell products are viewed more favourably because they allow greater breathability. In certain circumstances, professional reports and corrective work may be sufficient.

Ventilation Issues

Where the primary concern is poor airflow rather than structural damage, improving loft ventilation may reduce risk significantly.

Budget Considerations

While safety and lender requirements should always come first, re claim solutions can sometimes reduce disruption and expense where full removal is unnecessary.

How Much Does Spray Foam Removal Cost?

One of the most common questions homeowners ask is how much spray foam insulation removal will cost.

There is no universal figure because pricing depends on several factors, including:

  • The size of the loft
  • The thickness of the foam
  • Whether the foam is open or closed cell
  • Ease of access
  • Roof condition
  • Amount of manual extraction required
  • Waste disposal requirements

Closed cell foam generally takes longer to remove due to its density and adhesion. Older installations can also present additional challenges.

A professional survey is usually the best way to obtain an accurate quotation.
Can Spray Foam Be Removed Without Damaging the Roof?

Professional removal specialists aim to minimise disruption wherever possible. However, the reality is that some roof coverings or felt materials may already be compromised beneath the insulation.

This is another reason why experienced assessment matters. A careful removal process allows hidden problems to be identified before they worsen further.

Attempting DIY spray foam removal is strongly discouraged. Improper removal techniques can damage rafters, disturb roofing materials, and create safety risks within the loft space.

Why Professional Assessment Matters

Spray foam issues are rarely identical from one property to another. Some lofts remain structurally sound, while others conceal years of trapped moisture and deterioration.

An experienced inspection helps determine:

  • Whether the roof structure is healthy
  • Which type of foam is installed
  • Whether lenders are likely to raise concerns
  • If removal or re claim is the better solution
  • What corrective work may be needed

At Foam Away, the focus is always on giving homeowners clear, honest guidance rather than unnecessary alarm.

The Growing Importance of Spray Foam Specialists

As awareness around spray foam insulation grows, so too does the importance of using qualified specialists. Mortgage lenders, surveyors, and buyers increasingly expect professional documentation and evidence that work has been carried out correctly.

Homeowners across Dorset, Hampshire, Sussex, Birmingham, Coventry, and the wider Midlands are now seeking trusted experts who understand both the technical and property market implications of spray foam insulation.

The issue is no longer simply about insulation. It is about mortgageability, structural confidence, and protecting long term property value.
Frequently Asked Questions

Can spray foam insulation stop you getting a mortgage?

Yes. Some lenders may refuse mortgages on properties containing spray foam insulation, particularly closed cell foam, because of concerns surrounding hidden roof damage and limited inspection access.

Is spray foam insulation dangerous?

Not necessarily. However, poorly installed spray foam or trapped moisture beneath the insulation can contribute to roof problems over time.

What is spray foam re claim?

Spray foam re claim refers to corrective or partial remediation work designed to address specific concerns without always requiring complete removal.

Do all mortgage lenders reject spray foam insulation?

No. Policies vary between lenders. Some may request specialist reports, while others insist upon full removal before lending.

Is open cell or closed cell spray foam worse?

Closed cell spray foam is generally considered more problematic because it is denser, less breathable, and more difficult to inspect beneath.

Can you sell a house with spray foam insulation?

Yes, although spray foam may complicate the process if surveyors or mortgage lenders raise concerns during conveyancing.

Final Thoughts

Spray foam removal and spray foam re claim are not the same thing, and understanding the distinction is essential for homeowners navigating mortgage concerns or property surveys.

In some cases, targeted corrective work may provide an appropriate solution. In others, full removal is the clearest path forward. The right approach depends entirely on the property, the type of insulation installed, and the concerns identified during inspection.

What matters most is obtaining professional guidance from specialists who understand both the technical and financial implications involved.

For homeowners across the South Coast and the Midlands, Foam Away provides honest assessments, expert advice, and professional solutions tailored to each property. Whether you are facing a remortgage issue, preparing to sell your home, or simply seeking reassurance about your loft insulation, speaking with an experienced specialist can provide much needed clarity.

Get in Touch Today

If you are facing concerns surrounding spray foam insulation, obtaining professional advice early can make all the difference. Whether you have been flagged during a mortgage survey, are preparing to sell your property, or simply want reassurance about the condition of your roof space, Foam Away is here to help.

With extensive experience supporting homeowners across the South Coast and the Midlands, Foam Away provides honest assessments, expert guidance, and tailored solutions for both spray foam removal and spray foam re claim. Every property is different, which is why the team takes the time to fully inspect each installation before recommending the most appropriate course of action.

From Bournemouth and Southampton to Birmingham, Leicester, and beyond, homeowners trust Foam Away for professional service, clear communication, and a straightforward approach to resolving spray foam concerns.

To arrange a survey, discuss your options, or speak with a member of the team, get in touch with Foam Away today and take the first step towards restoring confidence in your property.
The Hidden Risks of Spray Foam Insulation Explained

Energy Efficiency

Spray foam insulation was once marketed as a revolutionary solution for improving energy efficiency within British homes. Promoted through government backed schemes and aggressive sales campaigns, it appeared to offer homeowners an easy route towards reduced heating costs and improved thermal performance.

However, the reality has become considerably more complicated.

Across England, increasing numbers of homeowners are now discovering that spray foam insulation can create serious problems when attempting to sell or remortgage their property. Surveyors are flagging concerns, mortgage lenders are becoming cautious, and many property owners are facing substantial removal costs simply to restore confidence in their homes.

For some, what began as an energy saving improvement has become a financial burden capable of delaying sales, reducing property values, and concealing damage within roof structures.

At Foam Away, we regularly assist homeowners who are confronting the consequences of problematic spray foam installations. Through our specialist Spray Foam Reclaim service, we help restore roof spaces, improve mortgageability, and provide practical solutions for properties affected by spray foam insulation issues.

What Is Spray Foam Insulation?

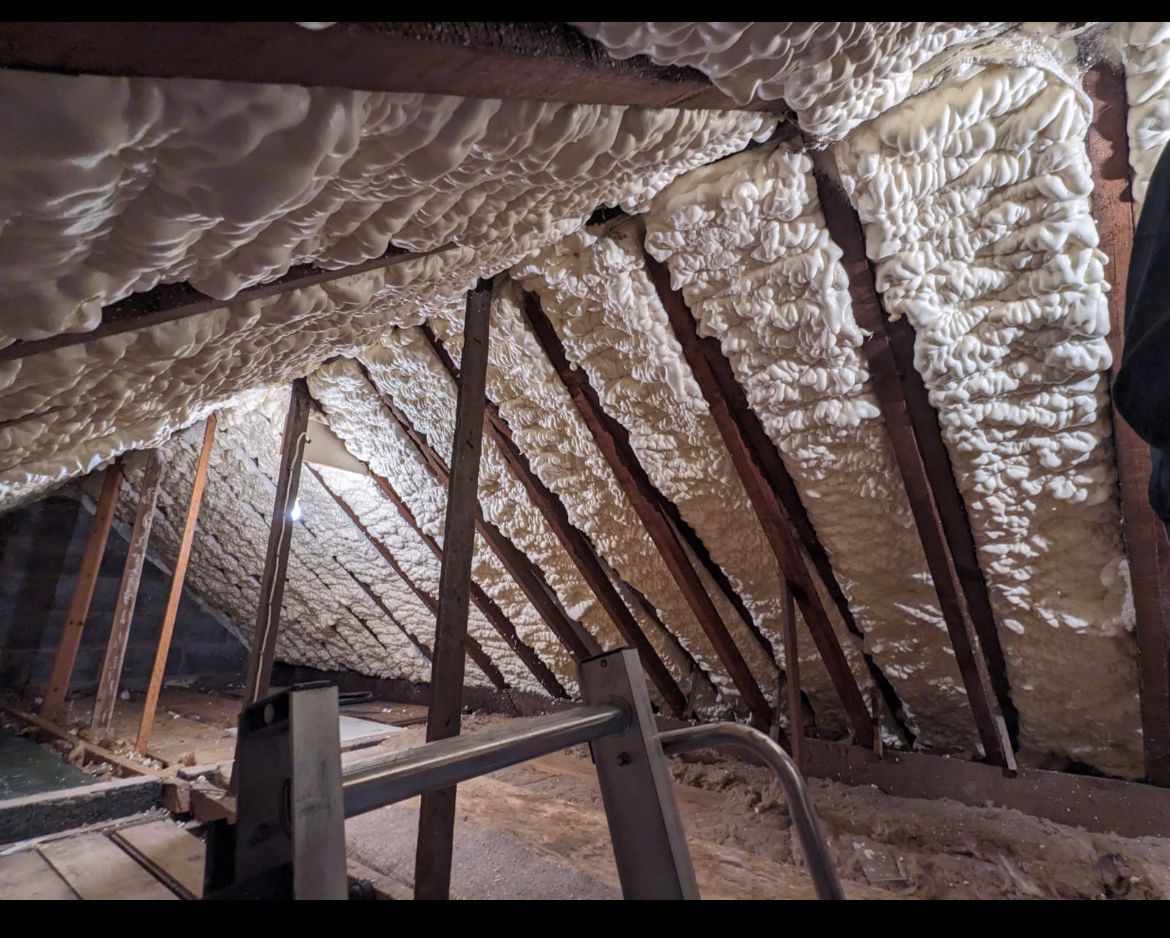
Spray foam insulation is a chemical product applied directly onto roof tiles, rafters, loft spaces, and cavity areas in order to create a thermal barrier. Once applied, the foam rapidly expands and hardens, forming an insulating layer intended to reduce heat loss.

There are two primary types of spray foam insulation used within UK homes.

Open Cell Spray Foam

Open cell spray foam is softer and lighter in texture. It allows a degree of air movement and is generally considered less rigid than its counterpart. Whilst some installers claim this makes it more breathable, it can still create significant complications when applied incorrectly.

Closed Cell Spray Foam

Closed cell spray foam is far denser and more rigid. It forms a hard surface that bonds tightly to roof timbers and tiles. Although it offers stronger insulation properties, it is also associated with greater structural concerns because it can trap moisture and restrict proper roof ventilation.

Mortgage lenders and surveyors often view closed cell foam with heightened concern due to the difficulty involved in inspecting roof structures hidden beneath the material.

Why Has Spray Foam Insulation Become Controversial?

The controversy surrounding spray foam insulation has intensified in recent years as mortgage providers and surveyors have become increasingly cautious.

Lenders such as Halifax, Santander, Barclays, Nationwide, and HSBC have all been linked to stricter scrutiny involving properties containing spray foam insulation. Whilst policies vary, many surveyors now identify spray foam as a potential risk factor during valuations.

This caution largely stems from several recurring concerns.

Hidden Timber Damage

Spray foam can adhere directly to timber rafters and roof structures, making inspections extremely difficult. Over time, trapped moisture may contribute to timber decay, mould growth, or rot that remains concealed beneath the foam.

Surveyors are unable to fully assess the condition of hidden structures without removal, which naturally increases lender hesitation.

Reduced Roof Ventilation

Traditional roof spaces rely upon airflow to regulate moisture levels. Spray foam insulation can obstruct ventilation pathways, allowing condensation to accumulate unnoticed over prolonged periods.

This may gradually compromise the integrity of roof timbers and create conditions favourable to damp related deterioration.

Difficulty Selling Properties

Many homeowners only discover the implications of spray foam insulation when they attempt to sell their property.

Potential buyers may struggle to obtain mortgage approval, resulting in delayed transactions or collapsed sales altogether. In some cases, homeowners are required to remove the foam before lenders will proceed.

Expensive Removal Costs

Removing spray foam insulation is neither simple nor inexpensive. Specialist removal techniques are often necessary to avoid damaging roof structures beneath the foam.

Costs vary significantly depending upon property size, foam type, accessibility, and installation quality. However, many homeowners face substantial unexpected expenses in order to restore lender confidence.

The Hidden Risks of Spray Foam Insulation

Whilst energy efficiency remains important, homeowners must also understand the broader implications associated with spray foam insulation.

Property Devaluation

Properties containing spray foam insulation may be viewed as higher risk by surveyors and lenders alike. This perception can negatively affect market value and buyer interest.

Even where no visible damage exists, uncertainty surrounding concealed roof conditions can discourage potential purchasers.

Mortgage Rejections

Mortgage refusals involving spray foam insulation have become increasingly common throughout England.

Surveyors acting on behalf of lenders may recommend further inspections or outright rejection until the foam has been professionally removed. For homeowners attempting to move quickly, this can create enormous frustration and financial pressure.

Condensation Problems

When ventilation becomes restricted, condensation may accumulate within roof spaces over many years. Unfortunately, because spray foam conceals underlying materials, moisture problems may remain undetected until considerable deterioration has occurred.

Structural Damage

In severe cases, roof timbers affected by trapped moisture may weaken over time. Repairing compromised structures can become extremely costly, particularly where extensive timber replacement is required.

Limited Roof Access

Routine roof repairs also become more difficult once spray foam has been installed. Roofers may struggle to identify leaks or inspect damage hidden beneath hardened foam layers.

Signs Your Spray Foam Insulation Could Be Problematic

Many homeowners remain unaware that their spray foam installation may already be causing concern.

Common warning signs include:

  • Surveyors raising concerns during property valuations
  • Mortgage applications being delayed or declined
  • Condensation or damp smells within the loft
  • Visible mould around roof timbers
  • Cracking or deterioration within roof structures
  • Difficulty obtaining home insurance
  • Concerns raised by roofing contractors

If any of these issues arise, seeking professional advice promptly is strongly advisable.

Can Spray Foam Insulation Damage Your Roof?

Unfortunately, the answer can be yes.

Whilst not every installation results in damage, poorly installed or incorrectly specified spray foam can create long term structural concerns. Closed cell foam is particularly problematic because it bonds aggressively to roof materials and restricts natural movement and ventilation.

Over time, moisture trapped against timber surfaces may accelerate decay. Roof repairs also become more invasive because foam often requires removal before proper inspection can occur.

This is precisely why many surveyors now approach spray foam insulation with caution.

Average Spray Foam Removal Costs Explained

The cost of removing spray foam depends upon several important factors.

These include:

  • The type of foam installed
  • The size of the affected roof space
  • Accessibility within the loft
  • The condition of the underlying timbers
  • Whether additional roof repairs are required

Whilst smaller removals may cost several thousand pounds, larger or heavily affected properties may require more substantial investment.

However, many homeowners find that removal becomes essential in order to proceed with property sales or mortgage approvals.

At Foam Away, we provide professional assessments designed to help homeowners understand the safest and most practical route forward.

What Is Spray Foam Reclaim?

Foam Away’s Spray Foam Reclaim service is designed to help homeowners restore confidence in their properties through professional assessment and removal solutions.

Our service focuses upon:

  • Safe spray foam removal
  • Roof structure inspections
  • Restoring ventilation pathways
  • Helping improve mortgageability
  • Supporting homeowners during property sales
  • Reducing long term structural risk

We understand the stress many homeowners experience after discovering spray foam related issues. Our aim is to provide practical guidance, transparent solutions, and professional workmanship throughout every stage of the process.

How Foam Away Helps Homeowners Across England

Foam Away supports homeowners throughout England who are facing concerns involving spray foam insulation.

Whether you are attempting to sell your home, secure a mortgage, or simply gain peace of mind regarding your roof structure, our experienced team can assist with tailored advice and specialist removal solutions.

We recognise that many homeowners feel overwhelmed after receiving negative survey reports or lender warnings. Through our independent expertise and Spray Foam Reclaim service, we help clients move forward with clarity and confidence.

Frequently Asked Questions

Why do mortgage lenders dislike spray foam insulation?

Many lenders are concerned because spray foam can conceal roof defects, restrict ventilation, and make structural inspections difficult.

Is spray foam insulation dangerous?

Spray foam itself is not always inherently dangerous, but poor installation and long term moisture retention can contribute to serious property issues.

Can spray foam insulation reduce property value?

Yes. Some buyers and lenders view spray foam as a potential risk, which may affect marketability and valuations.

Is open cell foam safer than closed cell foam?

Open cell foam is generally considered less rigid and more breathable, although both types may still create concerns if installed incorrectly.

Can spray foam insulation be removed?

Yes. Specialist services such as Foam Away’s Spray Foam Reclaim service can professionally remove problematic installations.

How can I tell if my spray foam insulation is causing problems?

Signs may include mortgage delays, damp smells, mould growth, surveyor warnings, or visible timber deterioration.

Conclusion

Spray foam insulation was once widely promoted as an innovative energy saving solution. Yet for many homeowners across England, the long term consequences have proven deeply concerning.

Mortgage complications, hidden roof damage, reduced property values, and costly removals are becoming increasingly common realities associated with poorly installed spray foam insulation.

If you have concerns regarding spray foam within your property, seeking professional guidance early can help prevent greater financial and structural difficulties in the future.

Foam Away provides trusted independent expertise alongside specialist Spray Foam Reclaim solutions designed to help homeowners restore confidence in their homes.

Whether you require a professional assessment, removal advice, or support during a property sale, our experienced team is here to help.

Is Spray Foam Insulation Affecting Your Mortgage Approval?

Spray Foam Insulation

For years, spray foam insulation was marketed as a modern solution for improving energy efficiency in British homes. Homeowners were told it would reduce heating bills, improve comfort, and help properties meet increasingly demanding energy standards. Yet across the United Kingdom, many property owners are now discovering an uncomfortable reality. Spray foam insulation can create serious complications when applying for a mortgage or attempting to sell a property.

From failed surveys to reduced valuations and outright mortgage refusals, the issue has become a growing concern throughout the property market. Homeowners who installed spray foam in good faith are now facing difficult questions from lenders, surveyors, and buyers alike.

If you have recently been told that spray foam insulation may affect your mortgage approval, you are certainly not alone. Fortunately, there are practical solutions available, and understanding the issue is the first step towards resolving it.

At Foam Away, we help homeowners across the UK remove problematic spray foam insulation safely and professionally, helping restore confidence for mortgage lenders, surveyors, and prospective buyers.

Why Are Mortgage Lenders Concerned About Spray Foam Insulation?

Mortgage lenders are ultimately concerned with risk. When a lender agrees to finance a property purchase, they need reassurance that the home remains structurally sound and retains its market value.

Spray foam insulation can create uncertainty in several ways.

Restricted Roof Inspections

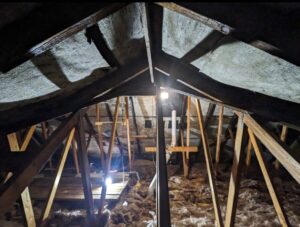
One of the main concerns involves roof timbers. Traditional loft insulation allows surveyors to inspect the condition of the roof structure easily. Spray foam insulation, however, adheres directly to the underside of roof tiles and timbers, often concealing signs of damage.

Surveyors may struggle to identify:

  • Timber decay
  • Water ingress
  • Condensation
  • Rot
  • Structural deterioration

If a surveyor cannot properly assess the roof, many lenders become hesitant to proceed.

Moisture and Condensation Risks

Certain forms of spray foam insulation can restrict airflow within the roof space. Poor ventilation may increase the risk of trapped moisture, which can eventually lead to damp conditions and timber decay.

Even where no visible damage exists, lenders often view the potential for hidden problems as a significant concern.

Difficulty Removing the Insulation

Another issue is removability. Spray foam can bond aggressively to roof timbers and tiles. In some cases, removing it without damaging the roof structure can prove challenging and expensive.

Mortgage providers may therefore worry about future repair costs or reduced resale value.

How Spray Foam Insulation Can Affect Mortgage Approval

The impact on mortgage applications can vary depending on the lender, survey findings, and the type of spray foam installed. However, many homeowners report similar difficulties.

Mortgage Refusals

Some lenders may decline mortgage applications entirely if spray foam insulation is present, particularly if surveyors cannot inspect the roof adequately.

Reduced Property Valuations

Surveyors may lower the property’s valuation due to perceived risks associated with spray foam insulation. A reduced valuation can affect borrowing amounts and delay property transactions.

Remortgage Complications

Homeowners looking to secure a better mortgage rate may encounter difficulties when remortgaging. Even if the property was previously accepted by another lender, updated lending criteria may produce a different outcome.

Equity Release Issues

Older homeowners seeking equity release products are also encountering problems. Some providers are unwilling to proceed while spray foam remains installed.

Delays During Property Sales

Buyers may become nervous after survey reports mention spray foam insulation concerns. Transactions can quickly stall while further investigations take place.

Which Mortgage Lenders Have Concerns About Spray Foam Insulation?

Lending policies continue to evolve, but many UK mortgage providers now approach spray foam insulation cautiously.

Surveyors working on behalf of lenders such as:

  • Halifax
  • Nationwide
  • Santander
  • Barclays
  • HSBC

may raise concerns depending on the type, condition, and installation method of the foam.

It is important to understand that policies vary significantly. Some lenders may still approve mortgages if sufficient documentation exists, while others may request specialist reports or recommend removal before proceeding.

This inconsistency is precisely why so many homeowners feel confused and frustrated.

Open Cell vs Closed Cell Spray Foam

Not all spray foam insulation is identical. Understanding the difference between open cell and closed cell foam is essential.

Open Cell Spray Foam

Open cell foam is softer and more breathable. It expands considerably during installation and is often considered less rigid than closed cell foam.

While some installers argue that it presents fewer ventilation concerns, lenders and surveyors may still raise objections.

Closed Cell Spray Foam

Closed cell foam is denser, harder, and more rigid. It creates a stronger seal and offers greater structural reinforcement.

However, because it bonds tightly to roof materials, surveyors often find inspections more difficult. Removal can also be considerably more labour intensive.

From a mortgage perspective, both forms of spray foam can create complications.

Signs Your Spray Foam Insulation May Be Causing Mortgage Problems

Many homeowners only discover the issue during the mortgage process. However, several warning signs may indicate that spray foam insulation is becoming problematic.

Survey Reports Mention Limited Roof Visibility

If a surveyor states that roof timbers cannot be adequately inspected, lenders may request further investigation.

Buyers Become Hesitant

Purchasers may withdraw or renegotiate after learning about spray foam insulation concerns.

Mortgage Applications Stall

Unexpected delays during underwriting can indicate that lenders are reviewing the property more carefully.

Requests for Specialist Reports

Some lenders now require independent spray foam assessments before approving finance.

Concerns About Roof Ventilation

Condensation or ventilation issues within the loft space can increase lender caution.

Is All Spray Foam Insulation Bad?

This is one of the most common questions homeowners ask.

The truth is more nuanced than many headlines suggest.

Spray foam insulation itself is not automatically defective. In some cases, it may have been installed correctly and may not currently be causing visible damage.

However, the broader issue lies in lender perception and surveyor accessibility.

Even where no structural problems exist, lenders may still hesitate because:

  • Roof timbers cannot be fully inspected
  • Future maintenance may prove difficult
  • Removal costs can be substantial
  • Marketability may be affected

As a result, perfectly functional spray foam installations can still create mortgage obstacles.

How Removing Spray Foam Insulation Can Help

For many homeowners, removal becomes the most effective route towards restoring mortgage confidence.

Professional spray foam insulation removal can help by:

  • Allowing full roof inspections
  • Improving lender confidence
  • Supporting smoother property sales
  • Reducing survey concerns
  • Restoring ventilation pathways
  • Improving marketability

In many situations, lenders and buyers become significantly more comfortable once the spray foam has been professionally removed.

The Spray Foam Insulation Removal Process

Many homeowners worry that removal will be highly disruptive. While the process does require specialist expertise, experienced professionals can complete the work safely and methodically.

At Foam Away, the process typically includes:

Initial Assessment

A thorough inspection determines:

  • The type of foam installed
  • The extent of coverage
  • Roof condition
  • Accessibility
  • Potential risks

Safe Removal

Specialist equipment and techniques are used to remove the foam carefully while minimising damage to surrounding materials.

Roof Inspection

Once the foam has been removed, the roof structure can be properly inspected for any signs of damage or moisture.

Clean Up and Disposal

All waste materials are removed responsibly, leaving the loft space clean and accessible.

Documentation

Homeowners may receive supporting documentation confirming professional removal, which can assist during mortgage applications or property sales.

Why Homeowners Across the UK Choose Foam Away

When dealing with mortgage concerns, homeowners need reassurance, professionalism, and experience.

Foam Away specialises in helping homeowners resolve spray foam related property issues with clear guidance and expert workmanship.

Clients choose Foam Away because we provide:

  • Experienced spray foam removal specialists
  • Professional and careful removal methods
  • Honest assessments
  • Friendly customer support
  • Mortgage focused solutions
  • Reliable service across the UK

We understand how stressful mortgage delays and survey issues can become. Our goal is to help homeowners regain confidence in their property and move forward without unnecessary complications.

Frequently Asked Questions

Can spray foam insulation stop you getting a mortgage?

Yes. Some mortgage lenders may refuse applications or request additional surveys if spray foam insulation is present.

Do all mortgage lenders reject spray foam insulation?

No. Policies vary between lenders, but many now apply stricter scrutiny when spray foam is identified.

Does removing spray foam help mortgage approval?

In many cases, yes. Professional removal can allow surveyors to inspect the roof fully and may improve lender confidence.

Final Thoughts

Discovering that spray foam insulation may affect your mortgage approval can feel deeply frustrating, especially if the installation was originally presented as a beneficial home improvement.

Yet the reality is that many UK lenders and surveyors are now approaching spray foam insulation with increasing caution. Whether you are selling your property, remortgaging, or applying for equity release, unresolved spray foam concerns can create significant delays and uncertainty.

The encouraging news is that solutions are available.

Professional spray foam insulation removal can help restore confidence for lenders, buyers, and surveyors alike while improving the long term marketability of your property.
If you are facing mortgage difficulties linked to spray foam insulation, Foam Away is here to help.

Contact Foam Away today to arrange a free survey and speak with a specialist about restoring your property’s mortgage potential.

Advisers Issue Mortgage Caution Regarding Spray Foam Insulation Use

Financial advisers and mortgage brokers have advised clients to exercise caution regarding spray foam and about the potential drawbacks of using spray foam roof insulation, noting that it could adversely impact their ability to re-mortgage or utilize equity release products.

As more individuals consider equity release as a way to access funds amidst the cost of living crisis, advisers are increasingly observing the negative repercussions for clients who have opted for spray foam insulation.

Traditionally, equity release lenders have been reluctant to accept properties with spray foam roof insulation, and many mortgage lenders also hesitate to offer mortgage deals for properties that have this type of insulation installed.

Contact us for further information

What are the issues with spray foam insulation?

Spray foam is a liquid foam that expands to form an insulating layer, commonly applied in roofs and attics. It has been in use for over three decades, often without problems. However, concerns have emerged specifically with closed-cell spray foam, which can potentially endanger roof timbers due to decay.

Once hardened, closed-cell spray foam is more rigid, making it a superior insulator compared to open-cell foam. However, this rigidity also means it acts as a barrier that blocks air release, potentially diminishing ventilation and leading to condensation issues.

Due to these factors, lenders are cautious about refinancing properties with spray foam insulation, worried that it might cause structural damage and decrease the property’s value.

Homeowners alike are being told to exercise Caution Regarding Spray Foam insulation

Spray foam insulation was among the improvements supported by the government’s Green Homes Grant scheme, which concluded in March 2022. This scheme offered to cover up to two-thirds of the cost of certain home improvements.

As reported by the Residential Property Surveyors Association and the Property Care Association, by December 2021, approximately 250,000 homes in the UK had installed spray foam insulation.

PFEP Wealth Management managing director, Richard Bishop told FTAdviser that homeowners would install the insulation without thinking they would be affected by the downsides, but the cost of living crisis has meant he is now seeing people regret their decision.

“With the problems with inflation and the cost of living rises we are seeing a small number of clients who didn’t realise equity release is also affected by foam installation,” Bishop said.

“The fitting companies have been telling clients the issue [with re-mortgaging], not making it clear that equity release is also affected. More elderly clients 12 months ago would not have thought they may ever use an equity release product in the future.”

He added: “As we advise clients, always think a decision you make today could have catastrophic effects on your future financial planning. You shouldn’t install anything in your home that could affect its overall value in terms of any possible future lending.”

Les Pick, director of manufacturing and adviser propositions at later life lender More2life noted that the challenge with spray foam is that it is not widely regulated.

“Incorrectly installed spray foam can cause serious issues over the long-term including water damage that can ultimately require the roof to be stripped back and replaced,” Pick said.

“Insulation is vital but homeowners need to be careful about the choices they make as they can impact the value of their home.

“Typically, equity release lenders are very wary of spray foam and few are able to accept it,” he added but pointed out that some lenders do accept it once it meets certain criteria.


    250,000 homes could be ‘unsellable’ due to spray foam insulation – report

    It has been reported that spray foam insulation could render hundreds of thousands of properties unsellable, with owners potentially unable to access equity release as well.

    Homeowners have been repeatedly cautioned about the risks and negative consequences associated with using spray foam insulation in their homes. The disadvantages of this type of insulation, notably the risk of moisture becoming trapped behind the foam, which can lead to decay, are estimated to affect around 250,000 homes. This issue underscores the importance of careful consideration and professional guidance when choosing insulation options for residential properties.

    Contact us

    Andy Wilson, an equity release specialist in Lincolnshire, told national newspaper The Times:

    “The reticence of lenders to accept properties with foam installed is causing distress to many homeowners who either cannot sell, mortgage or re-mortgage their homes.

    In many cases the foam may have caused no damage, but to measure this effectively the foam needs to be removed. As surveyors cannot say definitively that a property is free of defects (mainly rotten roofing timbers), it is safer and easier for lenders to decline to lend.”

    In March, The Royal Institution of Chartered Surveyors (RICS) introduced a new guide aimed at updating consumers about the Consequences of Spray Foam insulation in residential properties. RICS highlighted that spray foam is frequently marketed as a simple and straightforward solution. However, they emphasize that the installation of spray foam should be viewed as a major and significant modification to a home, necessitating thorough consideration and careful planning.

    In the same article, Chris Brown, the owner of Hydrogard, says they have “700 open inquiries” about compensation for spray-foam insulation. He added:

    “We probably take 35 to 40 calls a day, it’s staggering. We’re winning about four or five claims a week, and the average payout is somewhere between £7,000 and £10,000.

    The chances of us winning are very good, because in many cases the product shouldn’t be in their home.”

    Simon Storer, chief executive of the Insulation Manufacturers Association, said:

    “I understand there are plenty of examples where mortgage approvals have been made. Spray foam has been used in this country for 30 or 40 years. If there was the problem that people were claiming, you would see all these collapsed roofs. I know the lenders and surveyors have a job to do, and therefore we’ve worked with them to help them understand. The protocol is a method by which they can be satisfied about whether the job has been done correctly.”

    A spokesman for the Department for Levelling Up, Housing and Communities also said in the Times:

    “We are looking into the issues some homeowners are facing and are working with the industry and stakeholders to resolve this as quickly as possible.”

    Conversely, Simon Baker, Global President of Huntsman Building Solutions, highlighted some of the Consequences of Spray Foam insulation within the property market. He stated that:

    “High-performance insulation solutions like spray foam insulation are an optimal way for households to make their heating systems more efficient, will be critical to our country’s decarbonisation efforts and will help occupants save money on their heating bills. As such, Huntsman Building Solutions is currently consulting with the Government on how spray foam insulation can be used effectively as part of the Great British Insulation Scheme which is due to launch later this year.

    Huntsman Building Solutions acknowledges there are still misconceptions regarding spray foam insulation when it comes to lending decisions and equity release, and we empathise with individuals who face situations such as those quoted in your article. However, given the urgent need to radically upgrade the insulation standards of British homes, we must not marginalise spray foam insulation as it offers a real ability to decisively address many of the energy challenges we face, given its properties as an all in one highly effective insulator and air barrier.”


      Spray Foam Insulation and Mortgages

      Recent media and industry reports indicate that some homeowners are struggling to re-mortgage or sell properties with spray foam insulation.

      Incorrect installation can result in condensation, potentially damaging the roof structure.

      This article focuses on England.

      What is Spray Foam Insulation?

      This type of insulation is a method used to insulate homes, preventing heat loss, enhancing energy efficiency, and reducing energy bills.

      It is applied as a liquid using a spray gun, which then expands to fill the available space and sets into an insulating layer. It is commonly used for insulating roofs, lofts, and attics and comes in two forms:

      • Open Cell: This type remains soft after setting and is less prone to condensation compared to closed cell. However, it provides a lower level of insulation due to its lesser density.
      • Closed Cell: This type becomes rigid once set and offers better insulation than open cell. It also acts as a vapor barrier, which can reduce ventilation.

      Spray foam insulation was included in the government’s Green Homes Grant scheme, which ended in March 2022. This scheme covered up to two-thirds of the cost of energy efficiency improvements for homes.

      Potential Problems with Spray Foam Insulation

      Spray foam insulation has been used in many homes for decades, but recently, issues with timber-framed roofs have emerged. If incorrectly installed or used inappropriately, spray foam insulation might:

      – Reduce air circulation and ventilation within a roof space.
      – Cause dampness and condensation on the underside of a roof by forming an air barrier that prevents moisture from escaping.
      – Place timber-framed roofs at risk of decay.

      Additionally, spray foam insulation can be difficult and costly to remove. According to Checkatrade, the cost of removing spray foam insulation from the roof of a three-bedroom detached house is approximately £3,200 (or £40 per square metre).

      The Royal Institution of Chartered Surveyors (RICS) notes that the presence of spray foam may impact a surveyor’s valuation of a property, particularly if it has been applied incorrectly. The Home Owners Alliance (HOA), a consumer group advising homeowners, states that spray foam can cover a roof’s structure, making it difficult for surveyors appointed by mortgage lenders to inspect the condition of individual roofs and identify potential risks.

      Industry Guidance

      In November 2021, the Residential Property Surveyors Association (RPSA) and Property Care Association (PCA) published guidance, which has since been withdrawn. The guidance stated that, without technical information, it was “unlikely” that surveyors could accurately “comment on the condition of the timber roof structures or speculate on risk.”

      This guidance was withdrawn in October 2022 for a “full review.” The PCA and RPSA have been collaborating with lenders, surveyors, and the spray foam industry to develop inspection protocols and installation procedures.

      In March 2023, the PCA published an inspection protocol to help surveyors assess the risks of spray foam in pitched roofs. This framework aims to enable surveyors to evaluate the condition of individual roofs rather than make decisions based solely on the presence of spray foam. The PCA also developed training programs to help surveyors assess properties with spray foam and recommend appropriate actions.

      The PCA stated that the next step is for the spray foam industry to establish a “system of controls” for suppliers and installers, allowing “installations to be measured and verified” against product approval certificates.


        Warning Issued for Sellers Regarding Spray Foam Amid New Eco Scheme

        Government Urged to Exclude Spray Foam Insulation from New Eco+ Scheme

        The Government is being urged to exclude spray foam insulation from its new Eco+ scheme, which aims to improve the energy efficiency of the UK’s existing housing stock.

        A consultation on how the scheme will operate is currently open, but campaigners warn that this type of insulation should be excluded as it can make homes harder to sell.

        The Home Owners Alliance issued a statement yesterday expressing concern about the potential inclusion of spray foam insulation in the scheme.

        They claim that homeowners with this insulation in their properties face difficulties selling or obtaining equity release unless they spend thousands on its removal. This is because lenders are unwilling to provide loans for such properties.

        Paula Higgins, Chief Executive of the Home Owners Alliance, stated, “For years, spray foam roof insulation has been on a government list of approved measures. Homeowners have been able to access Government grants to reduce the cost of installing it in their homes. We are shocked and dismayed that homeowners doing the right thing are now being financially penalised: they either pay over the odds to remove the spray foam or remain stuck with homes they will find difficult to re-mortgage or sell.”

        Higgins emphasized that before spray foam insulation is included in the ECO+ scheme, the Government needs to resolve the issue. She added, “Homeowners can’t be expected to pay for government-backed energy-efficient measures only to have to pay twice over again to get it removed when they come to sell or re-mortgage. If lenders and surveyors can’t agree on a sensible view regarding spray foam insulation, then homeowners need to be warned upfront, and the government should require insulation companies to include a warning of the consequences of installation in their marketing materials.”

        Business Secretary Grant Shapps Launches New ECO+ Scheme

        Business Secretary Grant Shapps introduced the new ECO+ scheme as part of an energy-saving public awareness campaign.

        The Government has allocated £1 billion for ECO+, which will launch in April 2023 and run for the next three years. The scheme will extend support for measures such as loft insulation and smart heating controls to those who currently do not benefit from any other Government support for home upgrades.

        Of the £1 billion in funding available through ECO+, approximately 80% will be allocated to households in some of the least energy-efficient homes in the country—those with an EPC rating of D or below—and in the lower Council Tax bands.

        The Royal Institution of Chartered Surveyors (RICS) has expressed support for the new funding. A spokesperson told Estate Agent Today: “With the exception of materials that cause life safety concerns, RICS does not endorse or condemn any materials potentially included in grant schemes.”

        The Residential Property Surveyors’ Association (RPSA) created controversy last year among valuers, spray foam installers, and surveyors when it issued guidance recommending the removal of spray foam insulation from every property they visit. In a statement with the Property Care Association in December 2021, the RPSA said, “There may be as many as 250,000 homes with spray foam insulation in the loft, and the guidance being offered to their members is to adopt a highly cautious approach, recommending removal of the spray foam in almost every case.”

        This guidance has since been retracted pending a full review, following collaboration among industry stakeholders, supported by the Insulation Manufacturers Association (IMA), to standardize installation procedures and develop inspection protocols.

        Simon Baker, president of spray foam installer Huntsman Building Solutions, argued last night that spray foam insulation must be included in the ECO+ scheme. He stated, “As one of the most energy-efficient and innovative insulation products available today, spray foam insulation must be included in the Government’s new ECO+ scheme, helping to make necessary home improvements more affordable. When installed correctly, spray foam provides a highly effective layer of thermal insulation, helping homes retain more heat, reduce boiler usage, and slash heating bills. As the Government targets a reduction in energy demand of 15% by 2030, spray foam insulation will be essential in bringing the UK’s housing stock in line with modern requirements.”

        Baker emphasized that engaging a reputable and trained installer ensures quality installation. He also highlighted the need for lenders and their surveyors to better understand spray foam insulation and adjust their approach accordingly. “As spray foam insulation becomes a common fixture in homes across the UK, lenders must be prepared to confidently assess each installation on its own merits. To support this, HBS has developed a training program for surveyors, equipping them with the tools and insights to confidently approve correct and safe spray foam installations; the first training session is being launched in December 2022.”

        Baker added, “By collaborating with the IMA, alongside industry bodies such as the PCA, RICS, and the RPSA, Huntsman Building Solutions will be an important member of the team in developing a code of practice to be adopted by the industry. This would include requirements such as pre-installation assessments, the need for installations to be carried out exclusively by trained professionals, and jobsite inspections. Every step of installation should also be fully documented to provide lenders, surveyors, and homeowners the assurances they need to confidently adopt spray foam insulation.”

        To give homeowners greater confidence in adopting spray foam insulation, Baker noted that Huntsman Building Solutions already adheres to these requirements through its authorized installers. All installations are fully documented and come with a 25-year warranty, providing complete transparency and traceability.


          Has Spray Foam Loft Insulation Made 250,000 Homes Hard to Sell?

          Concerns Over Unqualified Firms Using Incorrect Foam Types, Hindering Home Loans

          Spray foam loft insulation is quick to install and promises to reduce energy bills. However, it can create difficulties when re-mortgaging, selling, and unlocking equity release. Lenders are worried that unqualified firms may not be using the correct type of foam, causing these issues.

          After their monthly energy bill soared to £500 this year, pensioners Rudi Szczerba and his wife Pat decided to quickly insulate their draughty terrace home.

          The timing seemed ideal when a salesman contacted them about a type of loft insulation called spray foam.

          Promising a 40 percent reduction in their bills, Rudi, 72, described the decision to install the insulation as a ‘no-brainer’.

          The foam was installed in September at a cost of £3,800. If energy bills remain high, they could recoup this expense in less than five years through savings.

          This is a decision that around a quarter of a million households have made in the past decade. However, many are unaware that spray foam insulation comes with potential drawbacks.

          Due to the unregulated nature of the industry, lenders are increasingly concerned that unqualified firms may not use the correct type of foam or properly assess a property’s suitability.

          Consequently, homeowners are finding it difficult to re-mortgage, unlock equity from their homes, or even sell them.

          Rudi and Pat’s Discovery

          Rudi, 72, and Pat, 75, both retired Polaroid employees, have encountered an unexpected scenario. The couple aimed to release £25,000 in equity from their newly improved £1 million end-of-terrace home in Knebworth, Hertfordshire.

          With no children to inherit their property wealth, they planned to gift the money to a lifelong friend in poor health to assist with his finances.

          However, their equity release adviser informed them that no lender would approve an equity release loan due to the spray foam insulation. They claim the installer never disclosed this potential issue.

          Equity release lifetime mortgages, available to homeowners aged 55 and older, have grown in popularity. According to a trade body, a record £3.1 billion of property wealth was withdrawn in the first half of the year.

          These mortgages allow homeowners to obtain a tax-free loan while retaining ownership. The loan is repaid when the home is sold, the borrower dies, or the borrower moves into care. However, homeowners with spray foam insulation are being excluded from the market.

          No equity release loan permits spray foam insulation installed after a property’s construction. Only one lender, More2life, will consider it if installed during construction and meeting strict quality criteria.

          Mark Gregory, chief executive of Equity Release Supermarket, states, “We think any spray foam installation company should inform homeowners that using spray foam would currently make them ineligible for a lifetime mortgage if they consider equity release.”

          Rudi and Pat are among the 250,000 households that have used spray polyurethane foam for insulation. Before the scheme was withdrawn in March 2021, spray foam was eligible for installation under the green homes government grant. It can insulate lofts, roofs, walls, and floors to improve energy efficiency.

          Industry Practices and Homeowner Concerns

          There is no industry code of practice, and installers are not required to inform homeowners that spray foam insulation could impact their ability to secure a mortgage or equity release.

          Lenders worry that some installers may have used the wrong type of foam or failed to verify if it was suitable for the home. This oversight can lead to rotten beams and costly roof replacements. Additionally, there is no straightforward way for a surveyor working for a mortgage lender to inspect the roof timbers after spray foam has been applied, making the home potentially un-mortgageable and unsellable, as Lorna Rolfe discovered.

          Lorna paid £5,000 to have foam installed in 2020 after seeing a Facebook advertisement. However, when she tried to sell her home near Dartmoor this summer, the buyer’s bank refused the mortgage after the surveyor noticed the foam insulation in the loft. To prevent the sale from collapsing, Lorna, an occupational therapist, spent £4,000 to have it removed.

          “I needed to sell my home to move closer to my 90-year-old uncle who has moved into a care home,” says Lorna. “The whole situation caused me a lot of stress and anxiety. I also found out the foam was flammable, toxic, and sprayed directly onto electrical cables. My life was at risk the whole time.”

          Claims management firm Hydrogard Legal Services is handling over 250 claims from vulnerable or elderly homeowners who were targeted by cold-callers and not informed that the foam could hinder their ability to sell their homes.

          Rudi and Pat are currently negotiating with a lender willing to review the guarantees provided by their installer. If they are denied, the installer has promised to remove the foam and refund their money.

          Kunle Barker, of architect and design studio Barker-Walsh, notes, “If spray polyurethane foam is not installed correctly, it may not provide the right ventilation, which could cause roof timber to rot.” Properly installed spray foam allows the roof to breathe and prevents moisture build-up.

          Homeowners are advised to work only with installers who conduct a hydrothermal evaluation, assessing the roof’s condition, the felt underneath, and the risk of condensation. While this documentation improves a homeowner’s chances of selling the property or obtaining equity release, it is not a guarantee.


            Surveyors to Revise Guidance on Controversial Spray Foam Insulation

            Trade Body for Independent Surveyors Retracts Guidance, Collaborates with Manufacturers to Reissue It

            Independent Surveyors Trade Body RPSA Revises Guidance on Spray Foam Insulation problems

            The Independent Surveyors trade body, RPSA, has reversed its stance on spray foam insulation.

            Spray Foam has been blamed for making approximately 250,000 homes ineligible for mortgages, as lenders fear its long-term effects. Many experts believe that spray polyurethane (PU) can cause damp issues within roofs, leading surveyors to often recommend its removal before a house purchase can proceed. This has tightened lending criteria and hindered many homeowners from selling their properties owing to spray foam insulation problems.

            The RPSA (Residential Property Surveyors Association) has now retracted its guidance from December last year, which advised surveyors to recommend the removal of spray foam and replacement of the roof if no detailed technical information was available.

            A group of stakeholders, supported by the Insulation Manufacturers Association (IMA) and including spray foam manufacturers and installers, surveyors, valuers, and lenders, is now collaborating to standardise installation procedures and develop inspection protocols to help with spray foam insulation problems.

            Factually Inaccurate

            Elizabeth Lalli-Reese, global vice-president of Huntsman Building Solutions, states, “We believe that the guidance issued by the RPSA in December 2021 was factually inaccurate, creating unwarranted concern among homeowners and lenders. We call for it to be retracted. Spray foam is a proven technology for making our homes more efficient and is a practical, sensible, and safe option for homeowners.”

            Alan Milstein, Chairman of RPSA, now says that the RPSA is reviewing this guidance. He comments, “We recognize the concerns raised by Huntsman and are encouraged by the positive way all parties have approached this initiative. Therefore, we have agreed to retract our current guidance pending a full review. Our goal is to republish it based on the outcomes from the industry group by Spring 2023, providing our members with the detailed knowledge necessary to risk assess any spray foam installation.”


              Portsmouth Woman Devastated as Foam Insulation Scam Renders Her Home Virtually Worthless

              When Susan Brameld agreed to have spray foam roof insulation installed in her Hilsea home, she had no idea she was opening the door to a nightmare that would leave her home virtually worthless.

              The 78-year-old widow, now residing in Fareham, was cold called by a spray foam insulation company in 2019 who mis sold spray foam insulation and persuaded to spend £4,800 under a government backed ‘green deal’ scheme aimed at reducing energy bills.

              However, just two years later, she had to pay an additional £5,500 to have it removed after discovering she had been scammed and mis-sold spray foam insulation. Her three bedroom home, valued at £360,000, had become unsaleable.

              In poor health, she discovered the problem only when she decided to downsize to a two bedroom bungalow after the death of her husband, Arthur.

              Susan discovered that banks and other lenders were unwilling to provide financing to potential buyers for properties with timbered roof spaces sprayed with foam insulation.

              Spray foam insulation has been in use for around 30 years and has gained popularity over the last decade. However, property surveyors caution that the foam, which expands and dries solid, can restrict air circulation, leading to roof timber rot and putting stress on a building’s structure.

              Concerned that other homeowners might fall into the same mis-selling trap, Susan wanted to warn others that the only way to sell their home might be to spend thousands of pounds to have the foam removed.

              ‘I now know I was scammed by the sales patter,’ she said, ‘but the company who installed it went bust and the work wasn’t guaranteed. I found the so-called guarantees invariably didn’t extend to any damage caused by rogue workmanship or dodgy technology.

              ‘I was told that it was government approved, I’d save more than £500 a year, and the more than adequate fibreglass roof insulation in my loft was a health hazard about to be declared illegal.

              ‘I confess I was quite happy with the job at the time, but I’ve had to put up with endless worry and sleepless nights when potential homebuyers kept pulling out of the sale because they couldn’t get a mortgage following a surveyor’s valuation.

              ‘I was devastated when one interested buyer showed me a survey report which put the value of my home at zero after pointing out it hadn’t been inspected before the spray treatment and I’d been poorly advised.’

              Construction writer and former university building lecturer Jeff Howell told Streetwise that he had been warning readers for many years about the dangers of spraying foam insulation onto the underside of roof slates or tiles.

              He said, “The claims for the product are nonsense and can cause irreparable damage to timber battens and rafters. It’s a bad idea and goes against building regulations, which require a clear 50mm (two inch) ventilated air gap between the insulation and the tiles or slates. If anyone feels the product was mis-sold to them, they should discuss it with their local trading standards office.”

              The Residential Property Surveyors Association (RPSA) and the Property Care Association (PCA) have also strongly condemned the use of spray foam insulation, warning that it could make around 250,000 homes un-mortgageable or ineligible for equity release.

              They convened a forum of industry stakeholders to evaluate the use and implications of domestic spray foam insulation products. The forum concluded that unless surveyors receive detailed information from installers at the point of inspection—including the condition of the roof and its flashing before and after insulation, the type of foam used, and the quality of roof space ventilation no property professional would likely speculate on the potential risk.

              In a damning conclusion, they stated that they had “failed to identify any circumstances” where a roof with this insulation could be given a “clean bill of health.” The guidance to their members was to adopt a highly cautious approach, recommending the removal of spray foam in almost every case.

              The original government ‘green deal’ scheme folded in 2015 due to poor uptake, but it gave rise to numerous dubious companies looking to exploit the home energy improvement market.

              Insufficient provisions were made to protect consumers from incompetent or scam operators, as there were no stringent measures requiring these companies to have procedures in place to provide detailed pre- and post-installation records to satisfy a surveyor’s inspection.

              A subsequent government ‘green homes’ grant scheme also failed quickly, facing criticism for bureaucratic application procedures and the availability of cheaper finance through banks. RPSA chairman Alan Milstein publicly warned that installers often prey on older, vulnerable homeowners, using certifications and ‘quality’ badges to convince people that spray foam would benefit their property.
              He added, “Sadly, the exact opposite is true. Homeowners may find their property difficult or impossible to sell, as lenders may refuse to offer mortgages or equity release funds, and they may have to spend thousands of pounds replacing their entire roof covering.”

              A Streetwise investigation of Companies House records revealed that a large number of spray foam insulation companies emerged to take advantage of the government’s green deal scheme. Many of these companies have since folded or been struck off for failing to produce accounts. They often resort to ‘phoenixing’—a legal loophole that allows under-capitalized firms to abandon their debts and resume trading by setting up a new company with a name similar to the original.

              A spokesman for Hampshire Trading Standards said, “We are aware of various scams targeting homeowners, and we advise people to always be cautious when employing tradespeople for repairs or improvements. Many scams involve tactics that should raise alarm bells, including cold calling, pressure to sign up quickly, and spurious claims about government grants. People can find reliable, Trading Standards-approved and verified trade services using our Buy With Confidence scheme at www.buywithconfidence.gov.uk. Further guidance and advice are available from the Citizens Advice Consumer Service at 0808 223 1133 or www.citizensadvice.org.uk/consumer.”


                Trusted & verified on

                Checkatrade
                AXA
                Bark
                City & Guilds
                Google Reviews
                Trustpilot
                Yell
                Checkatrade
                AXA
                Bark
                City & Guilds
                Google Reviews
                Trustpilot
                Yell